Productivity will play a major role in both the economy and the stock market during the coming years. Whether the massive investment companies are currently risking on the Artificial Intelligence craze ultimately proves successful will depend primarily on whether it leads to a period of prominent and sustained productivity gains.
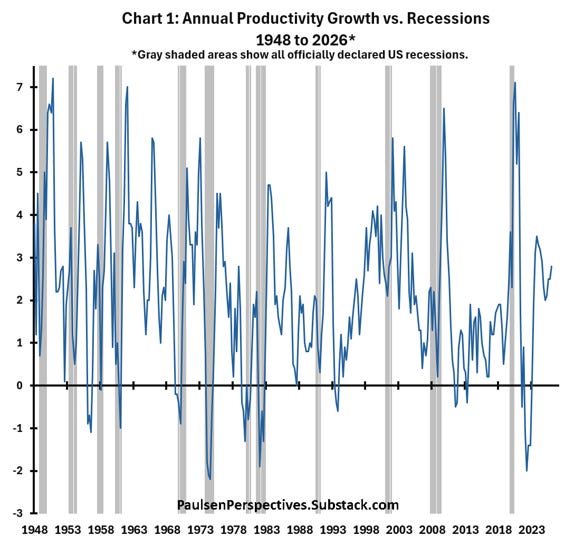
Chart 1 illustrates annual U.S. productivity growth since 1950. It has ranged between about -3% to +7%, averaging about 2.3% per annum since 1948. During the last year, U.S. productivity growth has risen by 2.8% causing many to believe the recent AI boom is already beginning to boost productivity gains. Although productivity growth since WWII has been volatile, sustained “actual or true” productivity booms are quite rare. Indeed, the recent improvement in productivity probably has more to do with ongoing “recessionary-like” conditions during the contemporary bull market rather than actual sustained productivity gains.